Enova Kills the Grasshopper Bank Deal, and the Market Takes a Billion Dollars Off Its Value
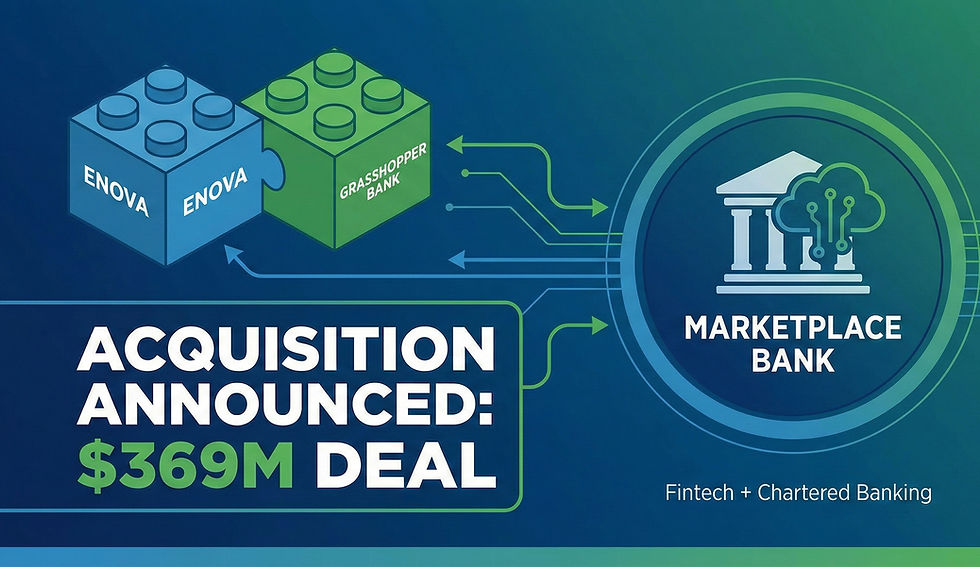
Quick Take: Enova International, the parent company of OnDeck, has withdrawn its applications with the OCC and the Federal Reserve tied to its planned $369 million acquisition of Grasshopper Bancorp, ending its bid to become a bank holding company. Shares fell more than 25 percent intraday in the first trading session after the announcement.

Nine months ago, Enova looked like it might become the thing fintech lenders have chased for a decade: a bank. This week it stopped chasing, and the market's reaction says more about what that charter was worth than anything in the press release.
The withdrawal
Enova announced after the close on Monday, September 14, that it had pulled its applications with the Office of the Comptroller of the Currency and the Federal Reserve Board related to the Grasshopper acquisition. The deal, announced last December at $369 million, would have made Enova a newly formed bank holding company with the digital-first Grasshopper Bank as its subsidiary, with closing expected in the second half of this year.
CEO Steve Cunningham did not go quietly. In the release, he argued that bank regulatory guidelines have not kept pace with how tens of millions of consumers and small businesses actually access credit, that regulators lack clear standards for nonbanks seeking to become banks, and that without those standards the process becomes "susceptible to political pressure and outside advocacy" rather than being governed by statutory factors. He closed with the line every analyst note will quote: Enova's future growth and success do not depend on becoming a bank.
The political pressure he's referring to has a paper trail. As PYMNTS reported, twenty state attorneys general wrote to the Fed, the OCC, and the FDIC in July asking them to deny banking privileges to companies the AGs contend use bank partnerships to get around state interest-rate limits. The letter named two deals specifically: Enova's Grasshopper acquisition and OppFi's pending purchase of BNCCORP and BNC National Bank. Enova had already flagged the risk in its own SEC filings, noting that approvals could come with conditions that erased the deal's benefits, and that closing was contingent on approval arriving without a burdensome condition. Two months after that letter, the application was withdrawn. The OppFi deal, the other one named, is now the test case to watch.
"I ran into an Enova representative in person at a recent industry conference and asked about the situation directly. They were polite but unwilling to share anything beyond what the press release says", said President of Funder Intel Shane Mahabir.
What the market said
Enova paired the withdrawal with reassurance: reaffirmed guidance from its July 23 earnings call, calling for roughly 25 percent revenue growth and 30 percent adjusted EPS growth in the third quarter, and 20 to 25 percent revenue growth with 30 to 35 percent adjusted EPS growth for the full year, plus a plan to accelerate share repurchases. As of June 30, the company had $218 million available for buybacks under its note covenants and $349 million under its board authorization. CFO Scott Cornelis pointed to strong quarter-to-date growth and credit trends.
The market was unmoved by all of it. In Tuesday's session, the first trading day after the announcement, ENVA opened at $176.22 against a prior close of $226.72, touched $167.85 intraday, a drop of nearly 26 percent, and finished at $173.61, down 23.4 percent on the day, per Yahoo Finance data. That single session took the company's market value to roughly $4.3 billion and left the stock far closer to its 52-week low of $103.02 than to its high of $267.45. (As of Thursday, September 17th, Enova stock has moved up to $178 mid-day.)

So guidance unchanged, buybacks accelerating, and the stock still gave up nearly a quarter of its value. The market wasn't pricing the quarter. It was pricing the strategic option Enova just surrendered: cheap, stable deposit funding for a lender that today funds through wholesale markets, and the legitimacy a charter confers. Investors may also have read a second, less comfortable message in the withdrawal, which is that if regulators and state AGs resisted Enova owning a bank, scrutiny of its existing bank-partnership economics isn't going away either.
What it means for the SMB side
For this industry, the relevant subsidiary is OnDeck, which Enova has owned since 2020, alongside Headway Capital on the small business side. Small business lending is a major share of Enova's book, and a bank charter would have transformed its cost of funds against bank-chartered competitors. That advantage is now off the table, and Enova goes forward the way most of this industry does: wholesale funding, securitizations, and partnerships, competing on underwriting and speed rather than cost of capital.
The bigger picture is the one Cunningham gestured at. The list of fintechs that started down the charter path and withdrew is long, and the list that finished it is short.
Whatever one thinks of the consumer-side pricing that actually drew the AGs' fire, the outcome sends the same signal the industry has received for years: the front door to banking remains extremely hard to walk through, and in this cycle, state pressure can reach deals sitting on federal regulators' desks.
Compliance Watch: The AGs' July letter is worth reading as a roadmap, not a one-off. Twenty states put federal regulators on notice that they view certain bank-partnership structures as rate-cap circumvention, and they have now shown they will intervene in merger applications, not just bring enforcement cases. Nonbank lenders relying on partner-bank origination, on either the consumer or commercial side, should assume that model stays under a spotlight regardless of who runs the federal agencies.
The deal is dead, the guidance stands, and the buybacks will flow. What Enova couldn't buy back this week is the version of itself that was nine months from being a bank.